An appraisal report (taxatierapport) is an independent, NWWI-validated statement of a home's market value that lenders require for a mortgage. Here is what it contains, what it costs, and the free alternatives to check value before you bid.
Buying a house
Why Do You Need an Appraisal Report in the Netherlands?
JH
Door Justin Hooker
9 minuten leestijd Laatst bijgewerkt op 14 september 2026
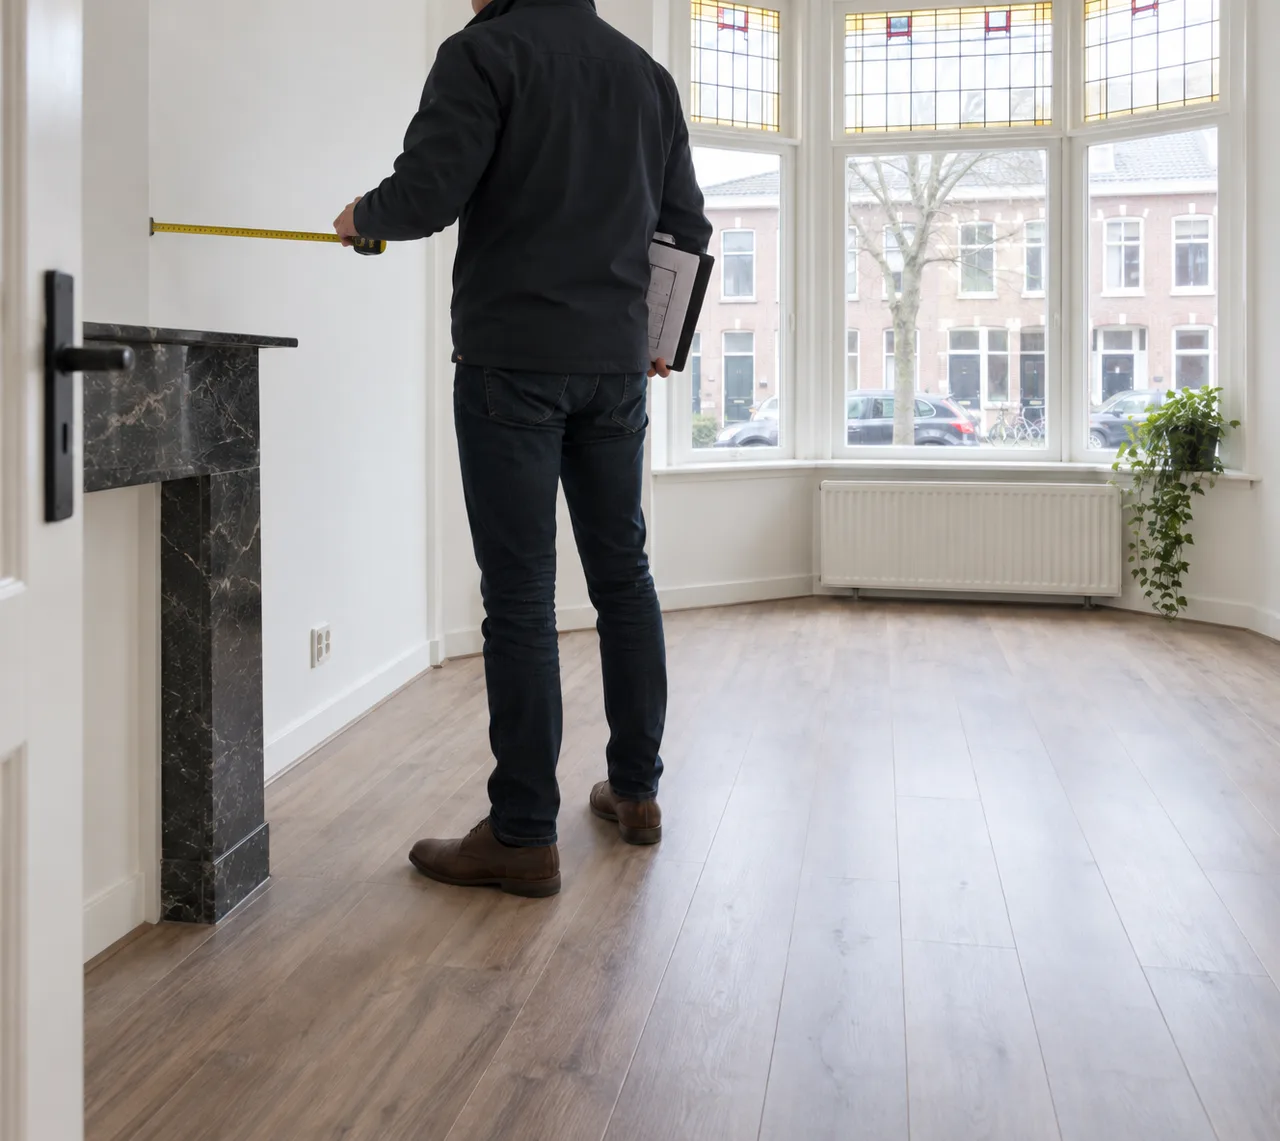
An appraisal report (taxatierapport) is an independent document that states the market value of a home, validated in the Netherlands by the Nederlands Woning Waarde Instituut (NWWI). You need one to secure or adjust a mortgage. Understand the home's value before you bid, so the report confirms a number you already trust, not one you discover too late.
Key takeaways
- An appraisal report gives an independent market value, and banks require it before approving a mortgage.
- The NWWI validates the report and assigns a unique code; once signed it cannot be changed without a formal decoupling procedure.
- You only need a validated report for a mortgage. For selling, buying orientation, or a WOZ objection, an unvalidated report or a free data report can be enough.
- An appraiser registered with the NRVT must be objective and independent, never tied to the purchase or sale.
- Walter's free data report is a faster first check on value before you order a paid appraisal.
What is an appraisal report?
An appraisal report, in Dutch a taxatierapport, is an independent statement of a home's market value, drawn up by a registered appraiser and, for mortgage use, validated by the Nederlands Woning Waarde Instituut (NWWI). It exists because a home has no fixed price: the asking price is what the seller hopes for, not proof of value. The report pins down a defensible number using concrete data, the location, year of construction, maintenance state, floor area, and recent sales of comparable homes nearby. For a first-time buyer that matters, because a lender books its loan against this figure, not against your enthusiasm. Want to understand how appraisers reach a number and where it can differ from the asking price? Our explainer on what determines the value of a house and the deeper appraisal report guide both unpack the mechanics.
Why do you need an appraisal report?
Banks and mortgage lenders require an appraisal report before they issue a mortgage, because they want certainty about the collateral behind the loan. The report is usually valid for about six months, though some lenders hold to a three-month window. If you finance with Nationale Hypotheek Garantie (NHG) or work with a mortgage adviser operating under AFM (Wft) rules, the appraised value is the figure everyone books against, not the asking price you fell for. This is general information, not Wft-regulated mortgage advice. You need the report to secure new financing or to adjust an existing mortgage, and the value in it also shapes how much you can borrow. Reading your mortgage quote alongside the appraisal helps you see the full picture, so the number that limits your loan does not surprise you at the notary.
What's in an appraisal report?
A validated Dutch appraisal report, drawn up to NWWI guidelines, contains:
- Property details: address, type, year of construction, layout, and gebruiksoppervlakte (usable floor area)
- Condition and maintenance: interior and exterior state, plus any visible defects
- Location and surroundings: amenities, accessibility, and zoning (bestemmingsplan)
- Kadaster (Land Registry) checks: ownership form and registered data
- Comparable transactions: recent sale prices of similar homes nearby
- Energy label and sustainability features
- Final market value: the objective figure, with any special assumptions noted
To make the report official, the appraiser visits the home in person to check the maintenance state, often after a building inspection. Getting the floor area right matters here, because square metres move the value, as our guide on how to measure living area explains. If you want the reasoning behind the number, determining the property's true value walks through it.
Not sure whether you need a full validated appraisal yet? A free Walter report gives you a data-backed value picture in minutes, an easier and faster first check than ordering a paid, validated appraisal.
What types of appraisal report are there?
In the Netherlands the practical split is between a validated and an unvalidated appraisal report, with a third, lighter option: a desktop or data valuation. A validated report is checked by the NWWI, which confirms the appraiser is authorised and reviews the substantiation before assigning a unique validation code. You need the validated version only to apply for or refinance a mortgage. An unvalidated report fits other situations: selling or buying a home and wanting the market value, objecting to your WOZ value, dividing assets after a break-up (though taking over the mortgage still needs a validated report), or settling an estate. A CMA or desktop valuation is faster and cheaper when you just need a data-backed number. The purpose decides which one applies, and it also decides the cost, since validation adds fees. Match the report to why you need it.
How is an appraisal report validated?
The NWWI (Nederlands Woning Waarde Instituut) validates appraisal reports from affiliated appraisers and makes sure every valuation is drawn up uniformly, according to clear guidelines. An appraiser registered with the NRVT (Nederlands Register Vastgoed Taxateurs) must act objectively and independently, and may never be connected to the purchase or sale of the home being appraised.
Before a report gets its validation code, the institute reviews several elements: whether the appraiser is authorised to appraise, correct substantiation of the market value, which sources were consulted, and whether there is any conflict of interest. Once the report is signed and validated, it cannot simply be changed. Adjusting it means the NWWI's formal ontkoppelen (decoupling) procedure, and only reports no older than six months can be decoupled. That is what makes the document trustworthy to a bank.
What should you watch out for in an appraisal report?
The biggest red flag in an appraisal report is a lack of independence. An appraiser who also brokered the sale, or who is tied to the buyer or seller, breaks the NRVT rule that a Register-Taxateur must be objective. Check that your appraiser is affiliated with the NWWI and registered with the NRVT. Other things to watch: comparable transactions that are old or in a different segment, a floor area that does not match reality, or a market value that leans on the asking price rather than on data. Honestly: an appraiser confirms a number that already exists, and rarely challenges whether the price itself is logical. That is exactly the gap you want to close before you bid. If you disagree with the related WOZ value your municipality set, the Waarderingskamer explains how to file an objection, and our WOZ objection FAQ covers the common questions.
What does an appraisal report cost, and are there alternatives?
An appraisal report is a real expense, and the total depends on several things that vary from one appraiser to the next. Ask upfront whether the quote includes the appraiser's fee, Kadaster (Land Registry) costs, municipal costs, administration costs, and VAT, because a low headline price can hide add-ons. Comparing a few appraisers is worth the effort, and a validated report costs more than an unvalidated one, so match the type to your purpose. Before you pay for a full appraisal, cheaper checks exist. A free WOZ value from your municipality gives a rough anchor (the same figure the Belastingdienst uses for the eigenwoningforfait), though it often lags the real market. A buying agent, often an NVM member, can estimate value from experience. And when you budget the one-off costs of buying a home, the appraisal belongs on that list.
"An appraiser is independent of the seller. That doesn't make them independent of the asking price."
Martine de Ridder, COO Walter Living.
That is Walter's whole point. We don't decide your bid, promise you a winning offer, or claim one universal fair price. We give you a clear value framework so you can reach a logical bid yourself. Walter doesn't gamble. Walter explains: pull a free Walter report on your target home and check its value before you commit.
frequently asked follow-ups
What is an appraisal report?
It depends on what you need it for, but at its core an appraisal report (taxatierapport) is an independent statement of a home's market value, drawn up by a registered appraiser. For a mortgage it must be validated by the NWWI. It uses location, condition, floor area, and comparable sales to reach a defensible figure.
How long is an appraisal report valid?
Usually about six months, but check with your lender first, because some accept only three months. Once signed and validated, the report cannot be changed without the NWWI's formal decoupling procedure, and only reports no older than six months can be decoupled at all. Plan your timing so the report is still current at completion.
What is the difference between a property data report and an appraisal report?
The short version: a data report is faster and cheaper, an appraisal is what the bank accepts. A validated appraisal is a formal, NWWI-checked document a lender books its loan against. A data or CMA report, like Walter's free one, gives you a value picture from public data to orient yourself before you bid. Only the validated appraisal works for a mortgage.
Do I always need a validated appraisal report?
Not always. You only need the validated version to apply for or refinance a mortgage. For selling, buying orientation, a WOZ objection, or dividing assets, an unvalidated report or a free data report can be enough. Match the type to your purpose, because validation adds cost.
Kopen? Plan je gratis oriëntatiegesprek
Kies een dag en tijd die jou uitkomt. We leren je plannen kennen en laten je precies zien hoe we je helpen je volgende huis te kopen — vrijblijvend en helemaal in jouw tempo.
Beschikbare tijden laden...
Buying a house
Bekijk alle Buying a house
Is it time to buy or keep renting for a while? Here are the pros and cons
Buying a house is a big step, especially if you are entering the housing market for the first time. For beginners, buying a home is often still a distant thought, partly because there are quite a few one-time costs involved in purchasing a home.
Steven van Wel
9 minuten leestijd
Walter Living is geregistreerd in Nederland op het adres Walter Tech, B.V. Singel 542, 1017AZ, Amsterdam. Ons KvK-nummer is 73708585 en ons BTW-nummer is NL859636033B01.
Diensten
Bedrijf
Liever even contact via WhatsApp? Stuur een appje naar +31 85 080 68 60